Editor's brief
Buying a car is often an emotional trap. Treating it as a technical procurement process—focusing on total cost of ownership, daily duty cycles, and empirical data—helps buyers avoid dealership pitfalls and secure a vehicle that serves their actual needs without financial strain.
#Car buying
#Total cost of ownership
#Vehicle procurement
#Auto negotiation
Buying a vehicle is frequently treated as an emotional experience, but for the buyer, it should be approached as a technical procurement process. The objective is to maximize utility and minimize the total cost of ownership while neutralizing the information asymmetry that dealerships use to their advantage. By shifting the focus from monthly payments to empirical data and engineering specifications, a buyer can avoid common financial pitfalls and secure a vehicle that aligns with their actual needs. Defining Requirements and Total Cost of Ownership A common error in vehicle selection is optimizing for a "worst-case scenario"—such as a rare camping trip—rather than the 95% of daily commutes. The primary duty cycle must dictate the choice. A driver in a dense urban environment will find the marginal utility of a full-size SUV negated by narrow parking structures and the inefficiency of stop-and-go energy consumption. Conversely, high-mileage highway commutes necessitate aerodynamic efficiency to reduce wind resistance and improve fuel or kilowatt-hour economy at sustained speeds. The purchase price is merely the entry point; the total cost of ownership (TCO) provides the real financial picture. This includes fixed costs, such as insurance premiums, and variable costs, such as scheduled maintenance and energy. For example, while electric vehicles (EVs) typically offer lower fuel costs, replacing high-performance tires can be more expensive due to increased vehicle weight and in...
Buying a vehicle is frequently treated as an emotional experience, but for the buyer, it should be approached as a technical procurement process. The objective is to maximize utility and minimize the total cost of ownership while neutralizing the information asymmetry that dealerships use to their advantage. By shifting the focus from monthly payments to empirical data and engineering specifications, a buyer can avoid common financial pitfalls and secure a vehicle that aligns with their actual needs.
Defining Requirements and Total Cost of Ownership
A common error in vehicle selection is optimizing for a "worst-case scenario"—such as a rare camping trip—rather than the 95% of daily commutes. The primary duty cycle must dictate the choice. A driver in a dense urban environment will find the marginal utility of a full-size SUV negated by narrow parking structures and the inefficiency of stop-and-go energy consumption. Conversely, high-mileage highway commutes necessitate aerodynamic efficiency to reduce wind resistance and improve fuel or kilowatt-hour economy at sustained speeds.
The purchase price is merely the entry point; the total cost of ownership (TCO) provides the real financial picture. This includes fixed costs, such as insurance premiums, and variable costs, such as scheduled maintenance and energy. For example, while electric vehicles (EVs) typically offer lower fuel costs, replacing high-performance tires can be more expensive due to increased vehicle weight and instant torque. Evaluating TCO over a five-year horizon prevents the trap of purchasing a vehicle with a low sticker price that proves expensive to maintain.
To maintain objectivity, buyers should utilize a checklist that separates functional requirements from luxury preferences. Functional requirements are non-negotiable specifications, such as cargo volume in liters or ISOFIX anchors for child seats. Luxury preferences, like ambient lighting or panoramic sunroofs, are secondary. Prioritizing Advanced Driver Assistance Systems (ADAS)—such as automatic emergency braking and blind-spot monitoring—provides a tangible increase in safety that outweighs the aesthetic value of premium upholstery.
Market Analysis and Vehicle Selection
A vehicle’s MSRP is an unreliable metric for actual value. Research should focus on a comparative analysis of hardware and long-term utility. Benchmarking multiple models within the same class reveals whether a price premium is justified by tangible performance gains, such as torque curves and energy consumption per kilometer, or merely by brand prestige. While professional reviews provide a baseline, they can suffer from "loaner car bias," where manufacturers provide pristine vehicles for short-term testing. True reliability data is found in owner registries and forums, where systemic failures—such as recurring software bugs in over-the-air updates—become apparent [1].
Reliability is a result of engineering consistency rather than brand loyalty. Data from organizations like Consumer Reports and J.D. Power help identify patterns in mechanical failure [1], [2]. In modern vehicles, reliability often inversely correlates with complexity; models with proven, iterative designs typically have fewer points of failure than those featuring experimental electronic interfaces. This principle extends to the model lifecycle: the first year of a new generation is often plagued by "early adoption" bugs, while the final year before a facelift typically represents the most refined version of that engineering cycle.
The decision between a new or used vehicle depends on the depreciation curve. Most internal combustion vehicles lose significant value immediately upon registration, making a three-to-four-year-old used car the optimal point for value retention. In the EV market, this is complicated by battery degradation and rapid leaps in charging technology. A used EV may have a lower entry price, but if the battery chemistry is outdated, the long-term value may be lower than a newer model with a current-generation battery and a valid manufacturer warranty.
Technical Evaluation and Physical Inspection
A polished exterior can mask systemic failures. Evaluation must begin with a vehicle history report to identify "title brands." A salvage or rebuilt title indicates the vehicle was previously declared a total loss, implying structural compromise or flood damage, which permanently lowers resale value and complicates insurance underwriting.
Physical inspection requires identifying build inconsistencies. Paint variance between panels, visible as a shift in hue or "orange peel" texture, typically signals a respray following an accident. Interior wear should be cross-referenced with the odometer; significant abrasion on the steering wheel or seat bolsters in a low-mileage vehicle is a red flag for odometer tampering or excessive idling hours.
Because modern faults are frequently electronic, a third-party pre-purchase inspection (PPI) using an OBD-II scanner is essential. A professional technician can find "pending" fault codes in the Engine Control Unit (ECU)—errors logged by the computer that have not yet triggered a dashboard warning light. Additionally, checking the oil filler cap for a milky emulsion can detect coolant contamination, a symptom of a failing head gasket. Tire evaluation should include the DOT date code; rubber older than six years is prone to dry rot regardless of tread depth.

The final assessment occurs during the test drive, focusing on Noise, Vibration, and Harshness (NVH). Highway speeds are necessary to identify wheel imbalance or alignment drift, which manifests as a rhythmic vibration in the steering wheel above 60 mph. In city environments, the focus shifts to transmission shift quality. Any hesitation or harsh jolts during downshifts can indicate solenoid failure or worn clutches. Stopping abruptly from moderate speeds reveals brake rotor warping, presented as a pulsating sensation through the brake pedal.
The Negotiation Framework
Dealerships often create information asymmetry, shifting the buyer's focus from the objective value of the machine to the emotional experience of ownership. To counter this, the buyer must treat the transaction as a procurement process. A critical tactical error is discussing the monthly payment too early. When a salesperson asks about a target monthly payment, they are attempting to shift the conversation toward the loan's amortization schedule rather than the vehicle's price. By extending the loan term from 60 to 84 months, a dealer can hide a higher purchase price and increase the total interest paid.
The only relevant metric is the "out-the-door" (OTD) price—the final sum including all taxes, registration, and fees. To maintain transparency, treat the purchase price, the trade-in valuation, and the financing terms as three isolated transactions. Finalize the purchase price first, settle the trade-in second, and discuss financing last. This prevents the dealer from shifting equity between these categories to maintain their profit margin.
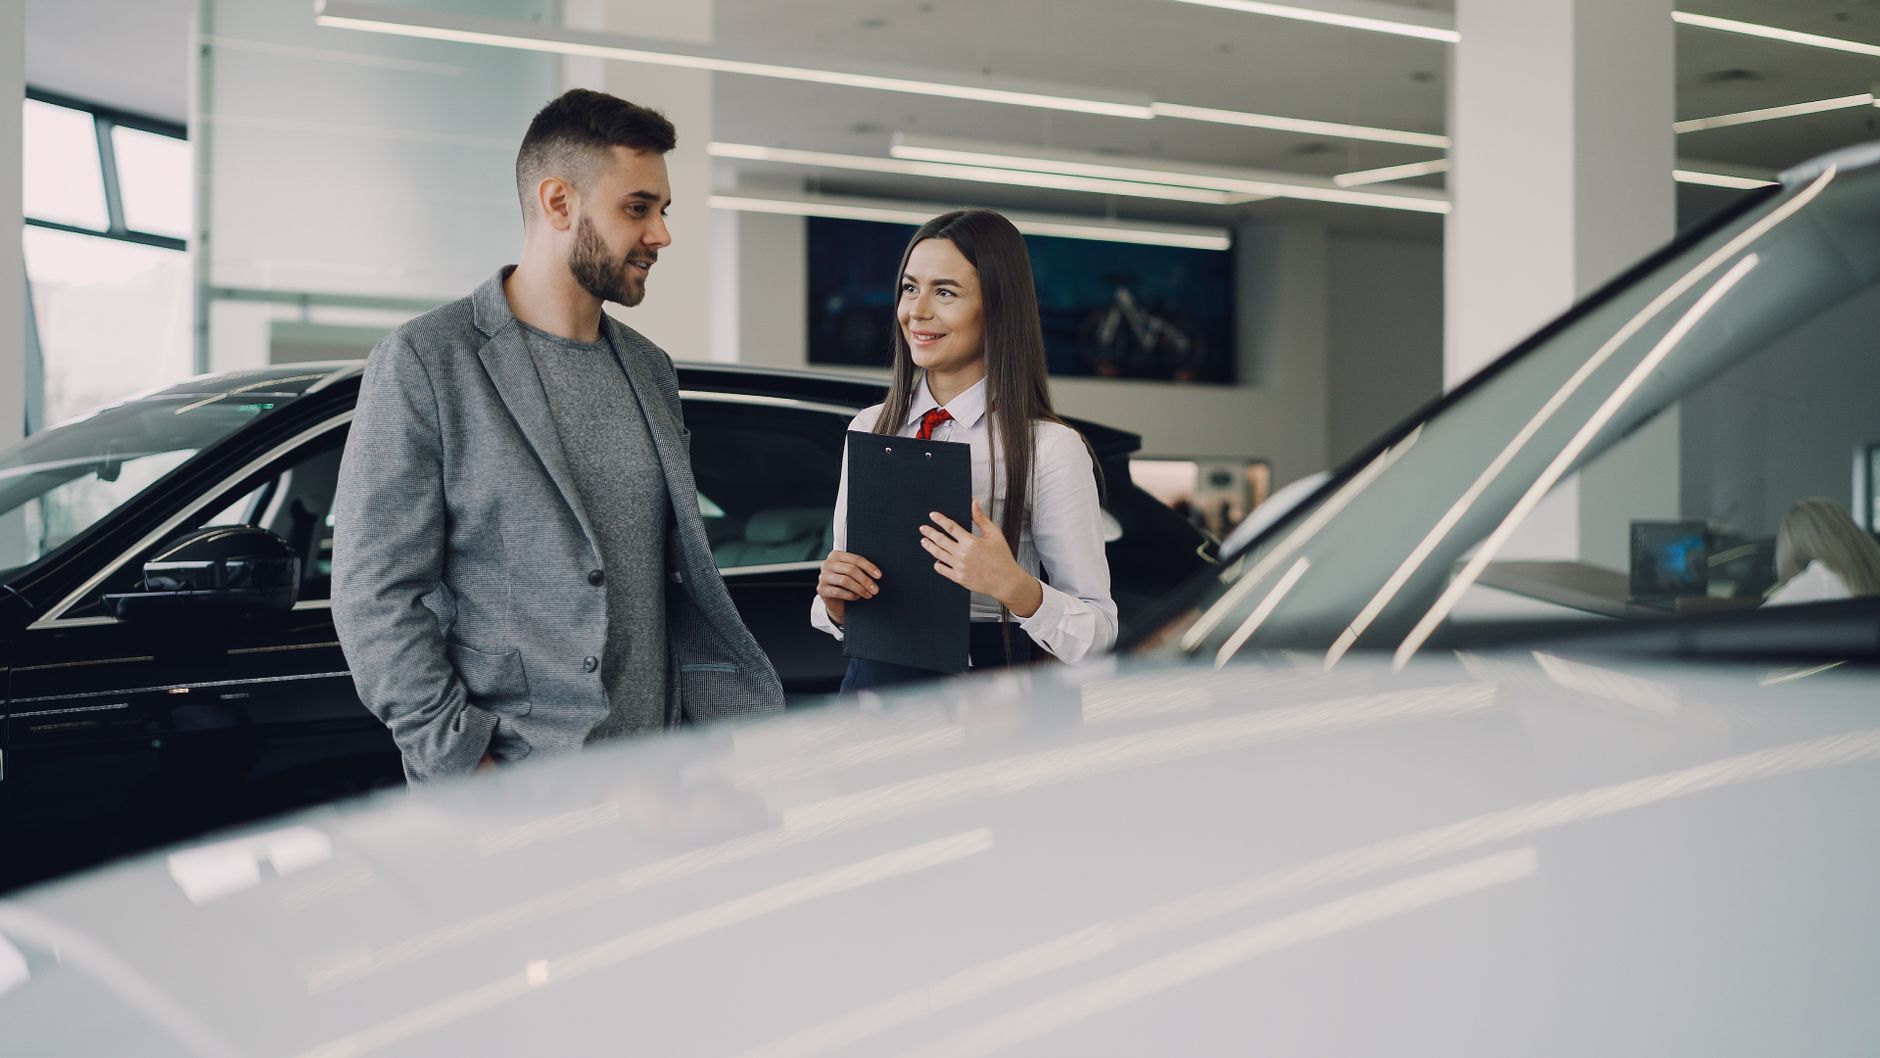
Negotiations should be grounded in empirical data from valuation tools like Kelley Blue Book or Edmunds [3], [4]. When a price exceeds these benchmarks, citing specific market data shifts the conversation from a subjective disagreement to a factual discrepancy. The initial offer should be a reasonable but low anchor, creating a psychological buffer for compromise. The most potent tool remains the willingness to walk away; because a car on the lot is a depreciating asset, the power dynamic shifts the moment the buyer demonstrates that the transaction is optional.
Closing and Final Verification
To avoid high interest rates, secure a pre-approved loan from a credit union or national bank before entering the dealership. This provides a mathematical baseline and forces the dealer to compete on the Annual Percentage Rate (APR) rather than the monthly payment. Avoid "negative equity," where a long-term loan results in owing more than the car's market value. The goal is to minimize total interest outlay by prioritizing the shortest sustainable term.

The Finance and Insurance (F&I) office is where high-margin "soft" charges—such as VIN etching, fabric protection, or overpriced extended warranties—are bundled into the financing. Because these are rolled into the loan, the buyer pays interest on them for years. A meticulous review of the final contract is necessary to strip these away. These add-ons are often flexible for the dealer and can be used as leverage to lower the actual price of the vehicle.
Technical verification is the final safeguard. The Vehicle Identification Number (VIN) on the dashboard and door jamb must match the title and bill of sale exactly to ensure the history report and warranty are tied to the correct chassis. Before signing the delivery receipt, a comprehensive physical walk-around is mandatory to identify transport damage or missing trim. Finally, ensure all verbal commitments, such as promised accessories, are explicitly written into the legal contract; if a feature is not listed in the line items, it does not exist.
Conclusion
Successful vehicle acquisition requires a transition from a consumer mindset to a procurement mindset. By prioritizing the daily duty cycle, analyzing the total cost of ownership, and insisting on an "out-the-door" price, buyers can eliminate the emotional levers used by dealerships. Relying on empirical data—OBD-II diagnostics, market valuation benchmarks, and pre-approved financing—ensures the vehicle remains a functional asset rather than a financial liability.
References
- Consumer Reports, "Vehicle Reliability Ratings," 2024.
- J.D. Power, "Vehicle Dependability Study," 2024.
- Kelley Blue Book, "Car Valuation and Market Trends," 2024.
- Edmunds, "True Cost to Own (TCO) Analysis," 2024.
I'm Kaori Nishimura from Japan. My path through Electrical Engineering has been anything but linear—after 11 years in the field, I've grown into someone who enjoys exploring automotive and gadget reviewer with a mix of curiosity and lived experience.